What "Accident" Means in Insurance Language
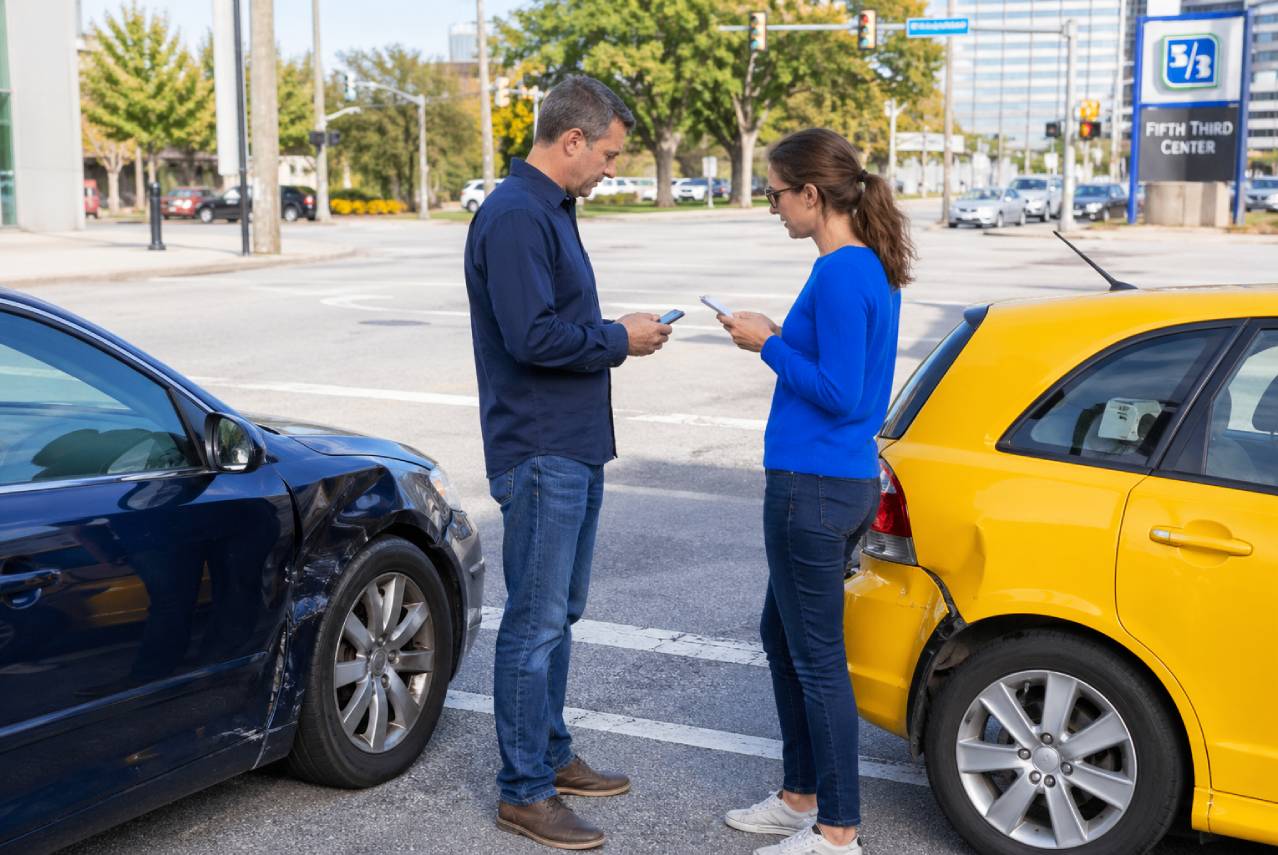
Most people use the word accident to describe almost anything bad that was not planned: a fender bender, a fall on a wet floor, a dog bite, even a punch thrown in a bar fight that "got out of hand." Insurance companies do not use the word that loosely. In an insurance policy, "accident" is a defined legal term, and how a court reads that term often controls whether a claim gets paid, reduced, or denied outright.
If you were hurt and an insurer is telling you the loss was not an "accident," it is worth understanding what that word actually means before you accept that answer.
The Everyday Meaning vs. the Policy Meaning
In ordinary conversation, an accident is any unfortunate event that happens by chance. Slip on ice, you had an accident. Drop your phone, accident. Get rear-ended at a red light, accident.
Insurance policies, however, almost always tie coverage to an "accident" or an "occurrence," and they define those words. A typical auto or general liability policy describes an accident as a sudden, unexpected, and unintended event that causes bodily injury or property damage. Three pieces matter inside that definition:
- Sudden and identifiable in time. Something happened at a particular moment, not gradually over years.
- Unexpected from the standpoint of the insured. The person covered by the policy did not plan or foresee the harm.
- Unintended. The insured did not mean to cause the injury or damage that resulted.
When all three pieces are present, the event is treated as an accident and coverage usually applies. When one is missing, insurers argue the loss falls outside the policy.
Why Insurers Fight Over the Word
Insurance companies write policies to cover fortuitous losses, meaning losses caused by chance. They do not want to pay for harm a policyholder caused on purpose, expected to happen, or allowed to develop slowly. So when a claim comes in, an adjuster's first job is to decide whether what happened fits inside the policy's definition of "accident" or "occurrence."
If it does, the company owes a defense and, usually, payment up to policy limits. If it does not, the company can deny the claim and walk away. That is why a single word in the policy can be worth tens or hundreds of thousands of dollars.
Common Situations Where "Accident" Gets Disputed
A few patterns come up again and again in Georgia injury claims:
1. Intentional acts dressed up as accidents
If someone deliberately swings at another person and lands a punch, most homeowners and liability policies will deny the claim because the harm was intentional, not accidental. The injured person is still hurt, but the insurer points to the policy's intentional-act exclusion. Skilled accident lawyers in Atlanta Georgia often have to dig into the facts to show the resulting injury was actually unexpected, even if some contact was intended.
2. Reckless driving and DUI crashes
A drunk driver did not "intend" to crash, but insurers sometimes argue the conduct was so reckless that the harm was substantially certain to occur. Georgia courts generally still treat DUI collisions as accidents for coverage purposes, which matters for victims pursuing an auto accident attorney in Atlanta for a serious injury claim.
3. Long-developing harm
Mold exposure, repeated chemical exposure, or injuries that build up over months can blur the line between "accident" and "process." Policies that require a sudden event may not respond, while policies written around "occurrences" sometimes will.
4. Multiple impacts in one event
Was a chain-reaction crash one accident or several? The answer affects how many policy limits apply. Insurers tend to argue "one accident" when limits favor them and "multiple" when it does not.
5. Truck and commercial vehicle crashes
Commercial policies often contain layered definitions and exclusions. When an Atlanta truck accident attorney is pursuing a claim against a motor carrier, the first fight is frequently over which policy responds and whether the event qualifies as a covered "accident" under each one.
How "Accident" Interacts With Other Policy Language
The definition of accident does not live alone in the policy. It works together with:
- Exclusions, such as intentional acts, criminal conduct, or expected injuries.
- Occurrence limits, which cap how much the insurer pays per accident.
- Per-person and per-accident limits, which determine how the available money is divided among multiple victims.
- Trigger language, which decides which policy year has to respond when injuries develop over time.
A claim that clearly involves an "accident" can still be reduced or denied if it bumps into one of these other provisions. That is why looking only at the accident definition is not enough. The whole policy has to be read together.
Why This Matters for Your Claim
If you are injured and the at-fault party's insurer is telling you the event "was not really an accident under the policy," that is not the end of the conversation. It is the beginning of a coverage dispute. Common defenses you may hear include:
- "Our insured intended the contact, so there is no coverage."
- "The injuries were expected given the conduct."
- "This is one occurrence, not several, so only one limit applies."
- "The harm developed over time and falls outside the policy period."
Each of those arguments can be challenged. Georgia law generally favors construing ambiguous policy terms in favor of coverage, and courts have repeatedly rejected insurer attempts to shrink the word "accident" beyond what the policy actually says.
A seasoned accident attorney in Atlanta will look at the policy language, the facts of how the event happened, and the relevant Georgia case law before accepting any denial. In many cases, what an adjuster calls "not an accident" turns out to be exactly the kind of loss the policy was written to cover.
What You Can Do If a Claim Is Denied on This Basis
If an insurer denies your claim because the loss "was not an accident," take these steps:
- Get the denial in writing. Ask for the specific policy language the insurer is relying on.
- Request a copy of the full policy. You or your attorney are entitled to see the definitions, exclusions, and endorsements being applied.
- Document the event in detail. Photos, witness statements, police reports, and medical records all help establish that the event was sudden, unexpected, and unintended.
- Do not give a recorded statement before talking to a lawyer. Adjusters sometimes use these statements to lock in language that supports a denial.
- Talk to an attorney quickly. Georgia has strict deadlines for injury claims, and coverage fights can take time to resolve.
Bottom Line
The word "accident" looks simple, but in an insurance policy it is doing a lot of heavy lifting. It decides who pays, how much, and whether a victim is left to chase the at-fault party personally. If you have been told your situation does not qualify as an accident, do not assume the insurance company is right. The language in the policy, the facts of the event, and Georgia law all have a say.
If you were hurt in Georgia and an insurer is pushing back on coverage, contact E. Albert Law for a free consultation. We will read the policy with you, explain what the insurer is really arguing, and pursue the full recovery you are owed.